

 Start AI Consultation


Technology-First
We built AI into every step of the mortgage journey — not as a gimmick, but because it genuinely finds better deals for clients faster.
Doing construction work for a contractor as a sole trader, limited company or partner? We help you find lenders who understand how subcontractor income is assessed.
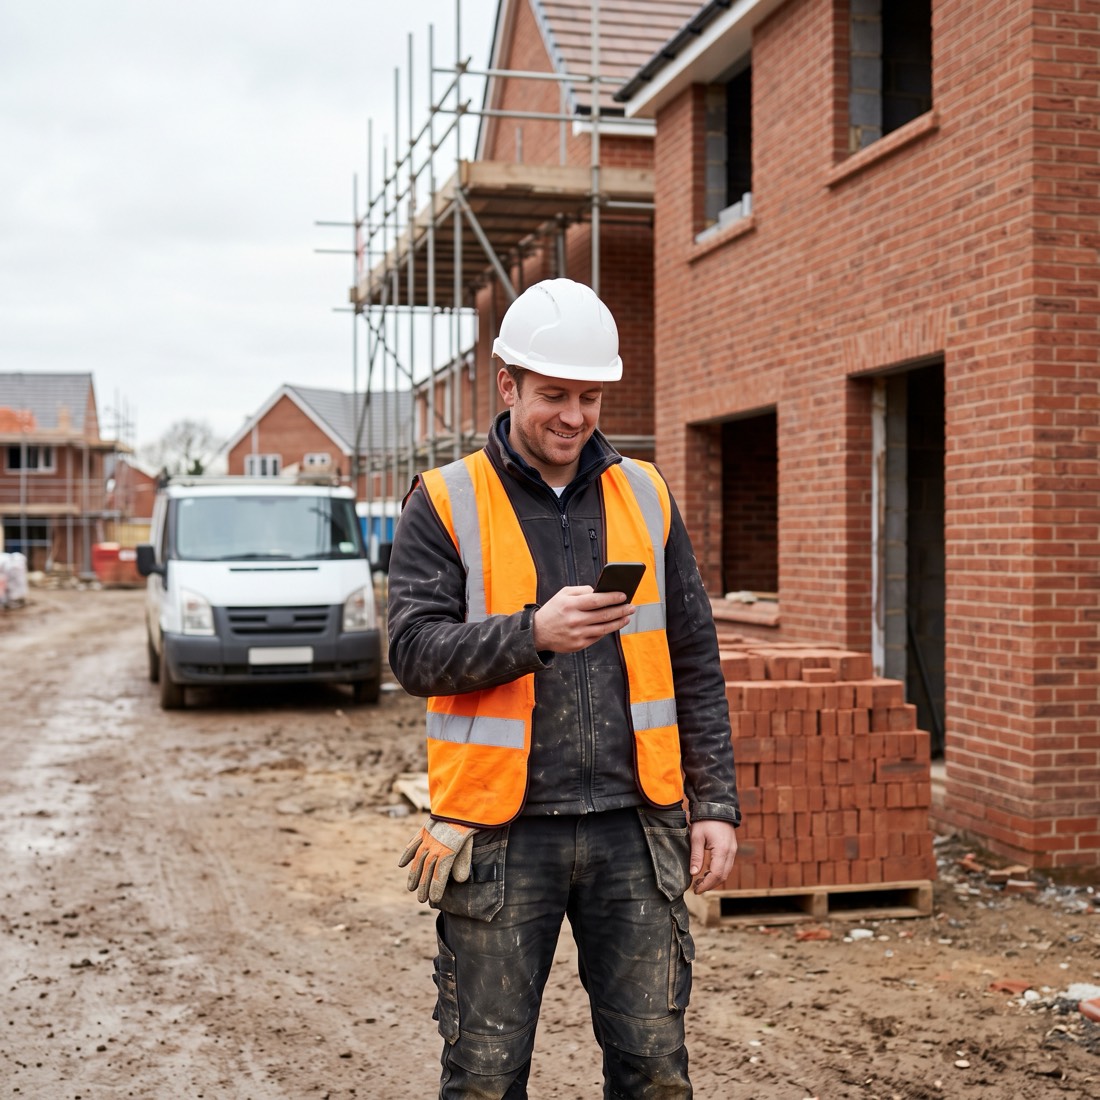
Understand how lenders may assess your income as a construction subcontractor.
Lenders don't all treat subcontractors the same way. Some assess you as self-employed, while others treat you as employed for your mortgage application, even though you're self-employed for tax.
Some lenders work from your gross income over the last 12 months, less materials or expenses. Others use the net profit shown on your SA302.
Your contractor must give you a monthly statement of what they've paid you and the deductions taken. Lenders commonly ask for 12 months of these.
Some lenders also ask for a contract confirming your work is ongoing, along with recent bank statements showing your income.
From first question to completion — our AI guides every step.
Tell our AI about your situation in minutes — no forms, just a conversation.
Our AI analyses 120+ lenders to find your best options instantly.
Get matched with the right lender based on your unique profile.
Your dedicated adviser manages the full application for you.
Completion day — you get the keys, we handle the paperwork.
Why us
Our values aren't a list of words — they're the principles behind every decision we make.
We built AI into every step of the mortgage journey — not as a gimmick, but because it genuinely finds better deals for clients faster.
Fully FCA regulated with qualified, experienced advisers. Your interests always come first.
We measure our success by our clients' success. 4.9-star Trustpilot rating from 2,400+ genuine reviews.
From contractors and self-employed to commercial finance — we handle complex cases that high street banks turn away.
Our AI mortgage assistant analyses your situation and matches you with the right product and lender — before you speak to an adviser.
Talk To AI AssistantExpert advice to help you secure the right mortgage.
Small improvements could unlock better mortgage rates.
Learn ways to strengthen your mortgage application.
Choose the option that best suits your financial goals.
Practical tips to build your deposit more effectively.
Know when to secure your next mortgage deal.
Reduce delays and improve your chances of approval.
Our calculators give you instant, accurate figures so you walk into every mortgage conversation fully prepared.
Full CalculatorEstimated monthly repayment
£1,390
Representative example — actual rates may vary
Contact us
Have a question about rates, pre-approval, or the buying process? We're here to make the mortgage side of things simple and stress-free. Drop us a line today.
Speak to a specialist mortgage adviser today
Everything you need to know about mortgages for construction subcontractors
