

Build A Protection Plan Around The Enterprise You've Built
Explore the main types of business insurance, from employers' and public liability to key person cover, and understand what each is designed to do.
 Start AI Consultation
WHY BUSINESS COVER MATTERS
Protect More Than Just Your Daily Operations
Business insurance can help protect against claims, interruptions and the loss of key people. Here are some of the main types of cover.
Employers & Public Liability
Employers' liability is a legal requirement for most employers. Public liability can cover claims if a member of the public is injured or their property is damaged because of your business.
Professional Indemnity
Can cover claims from clients who say they lost money because of your advice or a mistake in your work, subject to policy terms.
Business Interruption
Can help replace lost profit and cover ongoing costs if an insured event, such as a fire, stops your business from trading.
Directors & Officers (D&O)
Can help protect directors against claims made against them personally for decisions they make running the company.
CORE PROTECTION
Three Core Ways To Protect Your Business
Explore the main types of business protection and understand what each can be designed to do.
Business Property & Asset Cover
Can help protect your premises, equipment and stock against insured events such as fire, flood or theft, subject to policy terms.
Commercial Liability Protection
Can cover claims from customers, members of the public or employees, depending on the policies you choose.
Key Person & Shareholder Protection
Can pay out if a key person dies or becomes seriously ill, helping your business with lost profit, loan repayments or buying their shares, depending on the policy.
YOUR BUSINESS. YOUR PROTECTION.
Your Business Cover Can Change With You
Your insurance needs can change as your business grows, so it's worth reviewing your cover at each stage.
Founding & Launch
Consider public liability and professional indemnity, and check whether your clients or contracts require them.
First Employee Hire
Employers' liability insurance is a legal requirement once you become an employer, with cover of at least £5 million.
Office & Warehouse
Consider cover for your premises, contents, fit-out and stock.
Growth & Funding
As your board grows, directors' and officers' cover can help protect directors against personal claims.
Global Expansion
Working overseas? Check whether your policies cover work outside the UK, as territorial limits vary.
M&A & Succession
Selling, buying or passing on a business? Shareholder and key person protection can be part of planning for change.
BESPOKE BROKER PLACEMENT
Protection For Businesses With High-Risk Or Complex Operations
Some businesses need more specialist cover because of the work they do. These are some of the areas to discuss with an adviser.
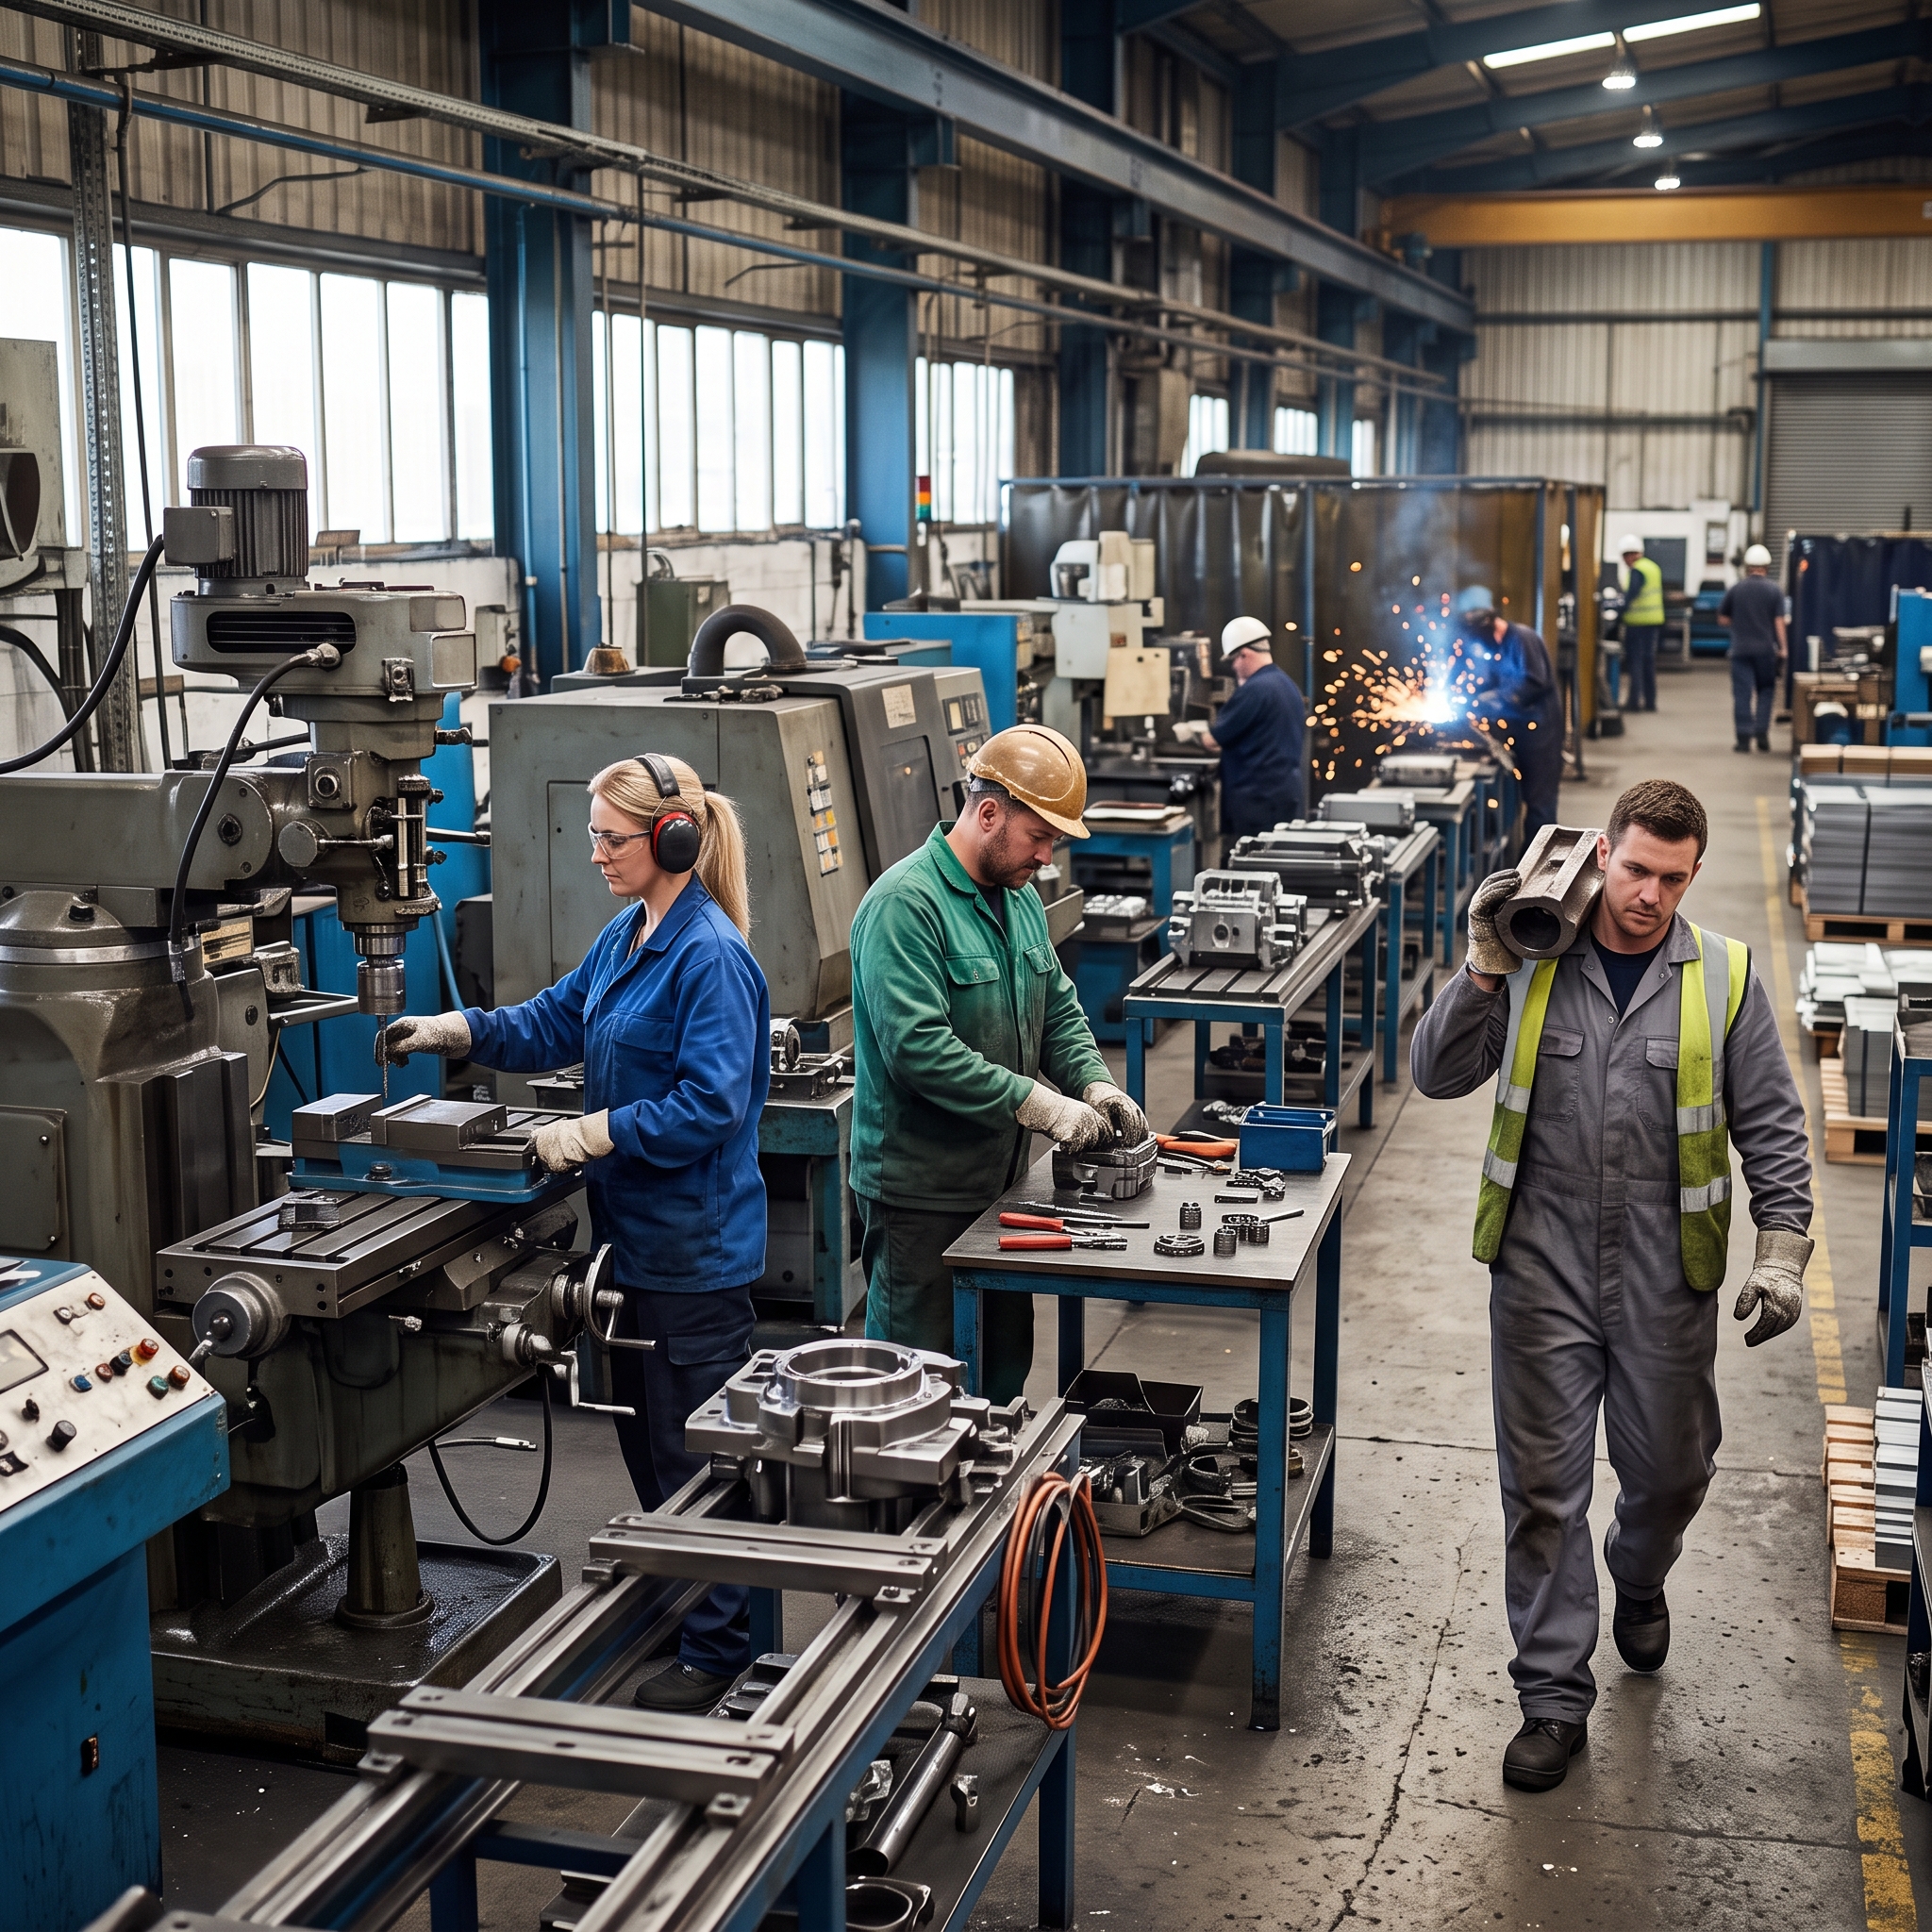
High-Hazard Trades & Hot Works
Work at height, hot works such as welding, or hazardous materials can need specialist liability cover.
Working Outside the UK
If you trade or work abroad, check your policies' territorial limits, as each policy sets out where it applies.
Supply Chain & Contingent Interruption
Some business interruption policies can be extended to cover losses when a key supplier or customer is affected by an insured event.
Tax Investigations & Legal Expenses
Legal expenses and tax investigation cover can help with professional fees if, for example, HMRC opens an enquiry, subject to policy terms.
UNDERSTANDING COVER
Know What Your Business Policy is Designed To Do
Every policy has its own terms, limits and excesses, so it's important to understand what yours covers.
Public & Employers Liability
Can cover legal costs and compensation if someone is injured or their property is damaged because of your business, up to your policy limit.
Professional Indemnity
Can cover legal costs and compensation if a client claims your advice or work caused them a financial loss.
Cyber Cover
Can help with the costs of responding to a cyber attack or data breach, such as restoring data and notifying customers, depending on the policy.
Business Interruption
Can help replace lost profit and pay ongoing costs while your business recovers from an insured event, such as a fire or flood.
Plant, Machinery & Stock Loss
Can cover the repair or replacement of equipment and stock damaged or lost through an insured event, subject to policy terms.
Employment Tribunals & Legal Disputes
Legal expenses cover can help with the cost of employment tribunal claims and other legal disputes, up to your policy limit.
How It Works
Simple Advice. Complete Protection.
Our advisers guide you through every step to ensure you receive suitable cover.
Free Consultation
A no-obligation call with your dedicated specialist adviser to understand your situation and goals.
Understand Your Needs
We take the time to evaluate your unique lifestyle, long-term goals, and budget.
Compare Options
We compare suitable options from the insurers we work with and explain the differences.
Choose Your Cover
Select the exact policy level you feel confident with, guided by clear advice.
You're Protected
Once you're happy, we help you put your cover in place, and we're here if your needs change.
WHY CLIENTS TRUST US
Protection Designed Around Your Business
Helping individuals, families and businesses protect what matters most.
Cyber Incident Response
Some cyber policies include access to specialist help to contain and recover from an attack.
Key Person Insurance
Can pay out if a key person dies or becomes seriously ill, helping your business cope with lost profit.
Commercial Vehicle & Fleet
Vehicles used for business need the right type of cover, such as business-use or fleet insurance.
Goods in Transit
Can cover goods while they're being transported, subject to policy limits.
Portable Tools & Laptops
Can cover tools and equipment you take from site to site against loss, theft or damage, depending on the policy.
Directors & Officers (D&O)
Can help protect directors against personal claims for decisions they make running the company.
Tax Investigation & Audit
Can help pay accountants' fees if HMRC opens an enquiry into your tax affairs, subject to policy terms.
Working Abroad
Policies set limits on where they apply, so check your cover if you work or trade outside the UK.
GET PREPARED
Make Your Business Cover Application Effortless
Having the right information ready makes applying for business cover quicker.
Company Details
Have your company number, business activities and trading history ready.
Premises Details
Insurers may ask about your premises, including the location, how the building is constructed and its security.
Lender & Lease Requirements
Check whether your commercial mortgage lender or landlord requires specific cover, so your policy can meet it.
Choosing Your Excess
A higher excess can lower your premium, but means you pay more towards each claim.
Policy Documents
Keep your policy schedule and employers' liability certificate to hand. You could be fined £1,000 if you don't display your certificate or make it available.
Annual Reviews
Review your cover each year, especially if your turnover, staff numbers or premises have changed.

Not Sure Which Mortgage Is Right For You?
Our AI mortgage assistant analyses your situation and matches you with the right product and lender — before you speak to an adviser.
Talk To AI AssistantContact us
Talk to our Mortgage Experts
Have a question about rates, pre-approval, or the buying process? We're here to make the mortgage side of things simple and stress-free. Drop us a line today.
Get Your Free Mortgage Consultation
Speak to a specialist mortgage adviser today
FAQ
Common Questions
Everything you need to know about business insurance
Is employers' liability insurance legally required? +
In most cases, yes. GOV.UK says you need employers' liability insurance as soon as you become an employer, with cover of at least £5 million, and you can be fined £2,500 for every day you're not properly insured. There are some exemptions, which GOV.UK lists.
What is business interruption insurance? +
Business interruption insurance can help replace lost profit and cover ongoing costs if an insured event, such as a fire or flood, stops your business from trading.
How are commercial property rebuild values calculated? +
Your buildings sum insured should reflect the full cost of rebuilding, including demolition, site clearance and professional fees, rather than the market value. A professional rebuild valuation can help.
Can we combine multiple commercial sites under one policy? +
Often, yes. Some insurers can cover several premises under one policy with a single renewal date.